
Deloitte Cyprus Faces Scrutiny Over Abramovich’s Billions as Leaked Records Raise Questions About Asset Ownership, Tax and Financial Transparency
An international investigation into Roman Abramovich’s offshore financial network has raised serious questions about the role of Deloitte Cyprus in approving historical corporate records that allegedly enabled billions of dollars in assets to be transferred retrospectively to the British Virgin Islands. The revelations have renewed concerns about the reliability of financial documentation, the responsibilities of professional advisers and the effectiveness of anti-money laundering controls.
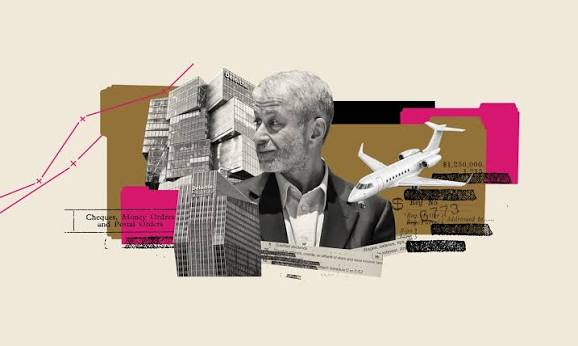
An investigation published on October 12, 2026, has placed Deloitte’s Cyprus operations under scrutiny over allegations that companies associated with Russian billionaire Roman Abramovich used backdated corporate documents to alter the recorded ownership of substantial assets, potentially reducing tax liabilities and limiting financial disclosure.
The findings, based on leaked corporate records, financial statements and correspondence examined by an international investigative collaboration, concern arrangements involving several Cyprus-registered companies, including Kravin Investments, Amiscan Investments and Electus Investments.
Investigators allege that corporate documentation was prepared or approved years after certain transactions supposedly occurred, creating records that presented assets as having been transferred from Cyprus to entities registered in the British Virgin Islands at earlier dates.
The distinction was financially significant. Cyprus had introduced changes to its tax and corporate transparency framework around its accession to the European Union in 2004.
Moving assets outside Cyprus, or establishing that they had been transferred before particular obligations arose, could affect how companies reported their holdings and calculated their liabilities.
The investigation raises questions not only about the underlying transactions but also about whether accounting firms and corporate service providers exercised sufficient independent scrutiny when reviewing documents used to establish ownership.
Deloitte Cyprus maintains that it complies with applicable laws. Abramovich’s legal representatives reject allegations of wrongdoing and maintain that there is no evidence he knew about, authorised or participated in the alleged falsification of documents.
Backdated documents and the movement of billions
The central allegations concern the difference between when corporate documents were actually prepared and when they purported to take effect.
Investigators identified arrangements in which paperwork reportedly created during the mid-2000s described transactions as having occurred several years earlier.
This practice could change the historical presentation of a company's assets without requiring the assets themselves to physically move.
An offshore company might continue holding investments, bank deposits or other property within a broader corporate network, while revised documentation attributes legal ownership to a different entity in another jurisdiction.
The investigation suggests that such arrangements were used to shift the reported ownership of substantial holdings away from Cyprus and into the British Virgin Islands, where corporate disclosure requirements were less extensive.
A broader examination of the leaked records identified more than 1,000 allegedly backdated corporate documents relating to more than 100 companies, with some documents reportedly assigned dates as much as five years before their actual preparation. The identified activity spanned 1999 to 2013, although investigators could not establish whether it continued afterwards.
Amiscan Investments: Luxury assets removed from Cyprus accounts
One of the most significant examples concerns Amiscan Investments, a Cyprus-registered company connected to Abramovich's holdings.
Draft financial statements for 2003 reportedly recorded assets worth approximately €578 million, including luxury yachts valued at €304 million, aircraft worth €122 million and property in France and Britain valued at approximately €109 million.
According to the investigation, an agreement prepared in 2006 carried the earlier date of January 4, 2003.
That document purported to transfer 19 subsidiaries from Amiscan to Kelvedon Worldwide, a company incorporated in the British Virgin Islands.
The timing was central to the arrangement because it represented the transfers as having occurred before the paperwork was actually produced.
Deloitte Cyprus reportedly examined the documentation and considered it sufficient to support removing the relevant holdings from Amiscan's financial statements.
By the time the accounts were approved in December 2006, the company's reported assets had fallen to approximately €65,000.
The investigation also highlighted correspondence from January 2007 in which a Deloitte Cyprus executive indicated that Amiscan's priority was to minimise disclosure concerning its subsidiaries.
The episode illustrates how retrospective corporate records can materially change the financial position presented to regulators and other users of company accounts, even where the underlying assets remain within an associated offshore network.
Electus Investments: Identical company names complicate ownership
A second arrangement involved Electus Investments, another Cyprus-registered company associated with Abramovich's business interests.
Electus was reportedly connected to Millhouse UK and assets valued at more than €8.6 billion.
The investigation found that arrangements developed in 2006 purported to transfer assets to a British Virgin Islands company also named Electus Investments.
However, the transfer documents carried a date of November 20, 2003.
The use of identically named companies in different jurisdictions introduced an additional complication: a company name alone cannot establish which legal entity owned a particular asset.
Corporate registration numbers, jurisdictions of incorporation and historical ownership records are necessary to distinguish one company from another.
When the Cyprus company's financial statements became publicly available, its reported assets had reportedly fallen to approximately €125,000.
The allegations therefore concern not simply the use of offshore entities but whether historical records accurately reflected when ownership changed and which company held the assets at the relevant time.
Kravin Investments: Bank deposits and potential tax liabilities
The third major example concerns Kravin Investments, a Cyprus company used within Abramovich's offshore investment arrangements.
Kravin received substantial proceeds in 2003 from the sale of shares in the Russian oil company Sibneft to Yukos.
The proceeds amounted to approximately €2.6 billion, with around €1.5 billion reportedly remaining in bank accounts and generating interest.
That interest created potential tax obligations in Cyprus.
Investigators examined correspondence indicating that, during 2005, Abramovich's associates, Deloitte Cyprus personnel and representatives of corporate services firm MeritServus discussed arrangements that would make the funds appear to have been transferred to the British Virgin Islands company Kelvedon Worldwide in 2003.
Unlike corporate ownership records, bank transaction histories could not simply be changed to erase deposits already made into Kravin's accounts.
Instead, the alleged strategy involved changing the documented ownership context surrounding those transactions.
The resulting accounts reportedly recorded total tax charges of approximately €13,000 for 2004 and 2005, despite the substantial sums involved.
The broader investigation described the arrangements as potentially enabling the avoidance of significant tax liabilities, although the precise legal treatment of the transactions would depend on the applicable tax rules and the underlying evidence.
Deloitte, MeritServus and the responsibilities of professional advisers
The findings also examine the relationship between Deloitte Cyprus and MeritServus, a Limassol-based corporate services business.
MeritServus operated within Deloitte Cyprus until 2005, after which the organisations continued working together.
Demetris Ioannides, who served as president of Deloitte Cyprus for almost two decades until 2005, subsequently became associated with MeritServus.
The investigation identified communications involving professional advisers and Abramovich's associates concerning the preparation and treatment of corporate documents.
These findings raise a particular concern where an accounting firm participates in preparing documentation that is subsequently relied upon in the preparation or audit of financial statements.
The possibility of circular verification arises when a document prepared from a client's instructions is later treated as independent evidence supporting the same client's financial position.
An audit opinion, legal memorandum or company secretary's certificate may provide useful assurance, but each serves a different purpose and has its own limitations.
A professional firm's reputation cannot, by itself, resolve conflicting dates, uncertain ownership histories or discrepancies between documents and contemporaneous financial records.
The investigation therefore raises wider questions about the degree of independent challenge applied to documents supplied by established clients and trusted intermediaries.
UK sanctions and a separate Cyprus tax case
The historical allegations have also attracted attention because of later sanctions imposed on individuals and businesses associated with Abramovich's offshore arrangements.
In April 2023, the United Kingdom sanctioned Demetris Ioannides and MeritServus, describing their involvement in offshore structures allegedly used to conceal assets connected to Abramovich.
The British authorities referred to arrangements involving assets worth approximately €860 million.
Ioannides declined to comment on the latest allegations through his lawyers, citing health problems.
Separately, Cyprus has pursued criminal proceedings relating to the management of luxury yachts through Blue Ocean Management, a company previously associated with Abramovich.
The company was struck off in July 2024 and reinstated by court order in June 2025.
The case also involves Meritservus Secretaries Limited and two former executives.
Prosecutors allege that tax and interest exceeding €26 million went unpaid and that required returns were not submitted.
These proceedings are distinct from the newly reported allegations about historical asset transfers.
Similarly, the sanctions imposed in 2023 do not automatically establish that transactions occurring years earlier constituted sanctions evasion. Such a conclusion would require evidence concerning the restrictions in force at the relevant time and the conduct of those involved.
Responses from Deloitte and Abramovich's representatives
Deloitte Cyprus has stated that it operates in accordance with applicable laws but has not provided a detailed public response addressing each of the specific transactions described in the investigation.
Abramovich's lawyers have rejected allegations of tax evasion and concealment.
They maintain that there is no evidence that the billionaire personally participated in, knew about or instructed the alleged falsification of documents.
His representatives have also emphasised that he relied on professional advisers, including Deloitte, to manage his corporate and financial affairs.
The investigation does not establish that Abramovich personally approved the disputed paperwork.
Nor do the reported allegations, on their own, amount to a criminal conviction against Deloitte Cyprus or the other parties named.
These distinctions are important because questions about the accuracy of corporate records, the legality of tax arrangements and potential criminal liability require separate legal and evidential assessments.
The anti-money laundering implications: Can ownership records be trusted?
Beyond the individual transactions, the revelations highlight a significant challenge for banks, auditors and anti-money laundering professionals: how to establish reliable beneficial ownership when the supporting documentation itself is disputed.
Corporate ownership checks commonly rely on incorporation documents, shareholder registers, financial statements, contracts and professional certifications.
However, the existence of multiple documents does not necessarily provide independent confirmation if those records originate from the same unverified account of a transaction.
The Financial Action Task Force's guidance on beneficial ownership emphasises the importance of adequate, accurate and up-to-date information, supported by verification using different sources.
The investigation demonstrates why the historical dimension of ownership can be as important as the current corporate structure.
Knowing who ultimately benefits from an asset today does not necessarily establish which company owned it several years earlier, when a transfer occurred or which tax obligations applied at that time.
For compliance professionals, the key issue is whether a documentary record accurately reflects an underlying transaction rather than merely presenting a legally convenient version of events.
Historical ownership requires more than a current company chart
A thorough review of a disputed ownership structure should establish a chronology covering incorporation dates, asset acquisitions, contractual agreements, approvals, document execution dates and regulatory filings.
Where documents are prepared retrospectively, reviewers should distinguish between the date on which a document was signed and the earlier date on which it claims a transaction became effective.
A later-prepared document is not automatically fraudulent. Companies may legitimately correct omissions or formally record earlier decisions.
Nevertheless, the explanation should be supported by contemporaneous evidence, particularly when a retrospective change materially affects reported assets, tax liabilities or disclosure obligations.
The Amiscan and Electus examples illustrate why company identities also require careful verification.
Two entities with identical names may be incorporated in different jurisdictions and possess entirely different legal identities.
Without checking registration identifiers and historical records, a reviewer risks treating documents concerning one entity as proof of another entity's ownership.
The risk of circular assurance
Another issue concerns reliance on professional documentation.
If an accounting record is prepared using information supplied by a client, and a subsequent assurance document relies on that same record, the second document may not independently verify the first.
This creates a risk that an unsupported assertion becomes accepted as fact through repetition across multiple professional records.
Effective verification therefore requires tracing material claims to their original supporting evidence.
Contemporaneous filings, independent transaction records, banking documentation and other relevant evidence can help determine whether a stated ownership history is credible.
Even public filings should be evaluated critically: they can demonstrate what was reported at a particular time without necessarily proving that the underlying statement was correct.
Why the allegations matter for Cyprus and international financial oversight
The investigation highlights the wider significance of Cyprus's historical role as a centre for international corporate structures and offshore asset management.
The country's accession to the European Union brought changes in tax treatment, financial reporting and transparency expectations.
The alleged restructuring of Abramovich-linked holdings occurred against that changing regulatory background.
The findings therefore raise questions about whether professional advisers adequately distinguished legitimate cross-border restructuring from arrangements designed to create misleading historical records.
Offshore companies are not inherently unlawful, and tax-efficient structures do not automatically constitute tax evasion.
The decisive questions concern the actual economic arrangements, the accuracy of the supporting documentation and compliance with the legal obligations applicable at the time.
For financial institutions, the case reinforces the importance of assessing professional certifications according to their evidential value rather than assuming that a recognised adviser's involvement resolves every uncertainty.
For regulators, it highlights the potential consequences when historical corporate records are revised without a sufficiently transparent explanation of what changed and why.
For company directors and compliance officers, it demonstrates the importance of preserving original documents, recording subsequent corrections and ensuring that material contradictions remain visible in internal assessments.
The broader lesson: Documentary consistency is not proof of authenticity
The central concern emerging from the investigation is that apparently consistent corporate documentation may still rest on an inaccurate historical premise.
A set of financial statements, contracts and professional certifications can present a coherent ownership structure while leaving unresolved whether the underlying transfers occurred when the documents claim.
That risk becomes particularly significant when billions of dollars in assets, substantial potential tax liabilities and complex multinational ownership arrangements are involved.
The investigation does not establish that every disputed transaction was unlawful, nor does it resolve the individual responsibility of every professional or corporate participant.
It does, however, demonstrate why the reliability of ownership information cannot be assessed solely by the number of documents available or the standing of the professionals who prepared them.
The fundamental question is whether the recorded ownership history can withstand independent examination against the evidence available at the time.
The allegations involving Deloitte Cyprus and Abramovich-linked companies place that question at the centre of a wider debate about financial transparency, professional accountability and the effectiveness of anti-money laundering controls across international corporate networks.
As scrutiny continues, the case serves as a reminder that effective financial oversight depends not merely on obtaining documentation, but on establishing whether that documentation provides an accurate and independently verifiable account of economic reality.
By fLEXI tEAM


Comments